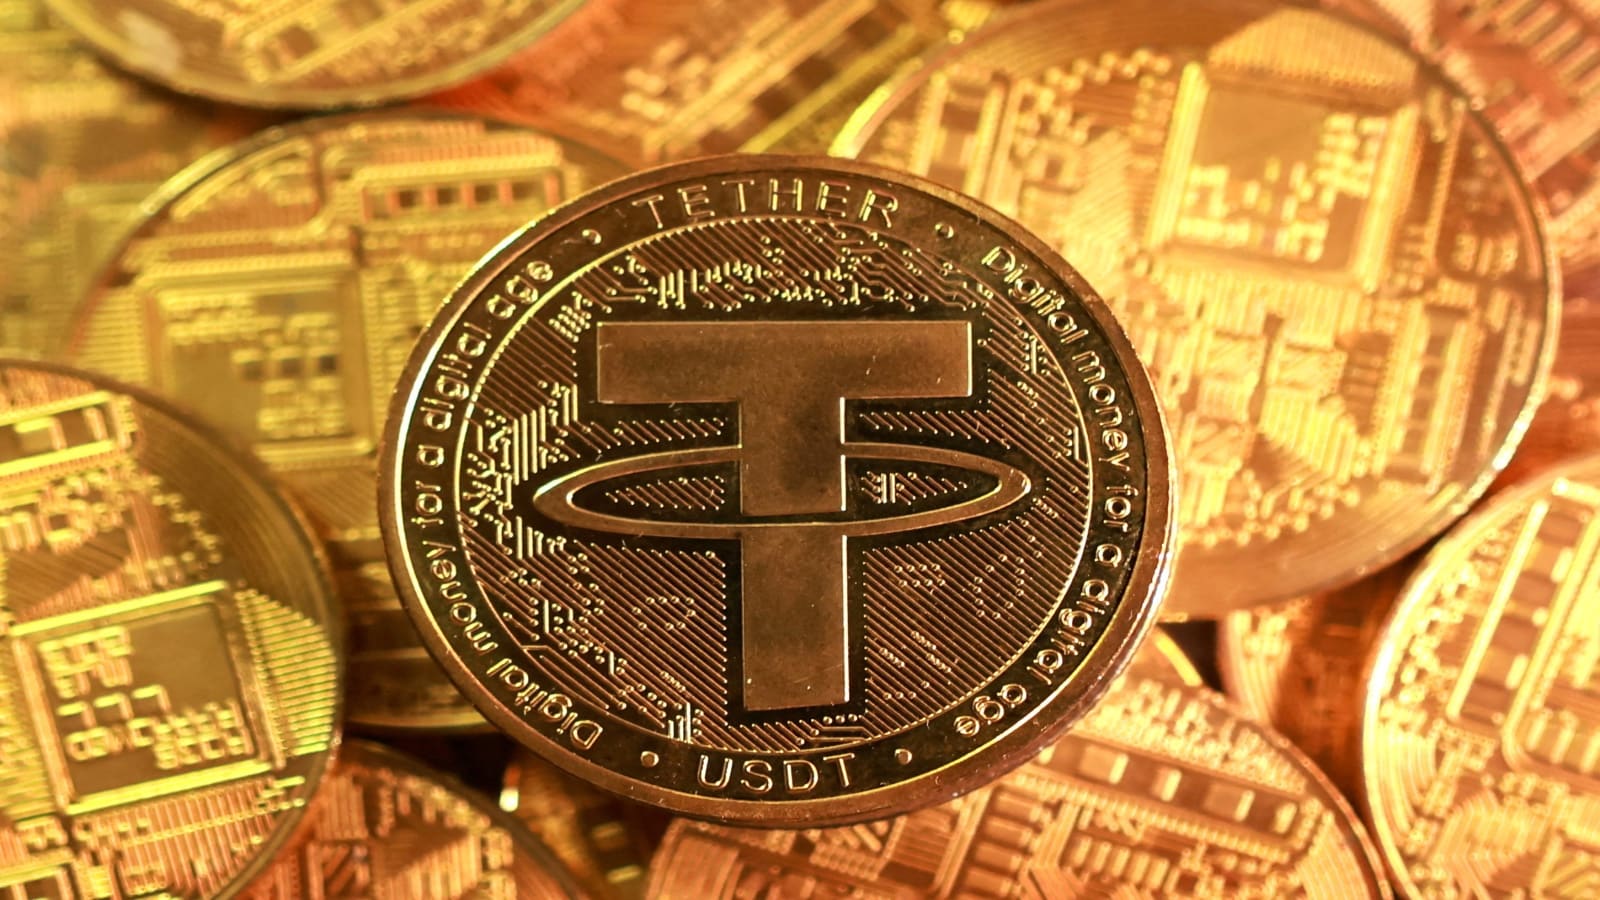
In a recent interview, Agustín Carstens, the governor of the Bank for International Settlements (BIS), warned that stablecoins – digital assets pegged to a fiat currency or a basket of assets – are not a credible means of payment when used at scale. While stablecoins have attracted considerable investor interest because they promise the price stability of traditional money combined with the speed of blockchain transactions, Carstens argued that the underlying infrastructure and regulatory oversight are insufficient for them to replace conventional payment rails. He highlighted that most stablecoins are issued by private firms that lack the balance‑sheet strength and public‑sector accountability that central banks provide, making them vulnerable to runs and operational failures.
Carstens also pointed to the growing apprehension among regulators worldwide about the potential for stablecoins to facilitate money‑laundering and other illicit activities. The BIS chief noted that, unlike traditional banks, many stablecoin issuers operate across borders with limited transparency, complicating the task of monitoring suspicious transactions. While the United States has taken a relatively proactive stance in drafting comprehensive crypto regulations, Carstens said that jurisdictions outside the U.S. are lagging, creating a patchwork of rules that could undermine global financial stability.
The BIS chief’s remarks come at a time when Indian policymakers are actively debating the regulatory framework for digital assets. The Reserve Bank of India (RBI) has already imposed a ban on private cryptocurrencies in 2023 and is now evaluating the role of central bank digital currencies (CBDCs) as a sovereign alternative to private stablecoins. Carstens’ cautionary stance adds weight to the argument that India should prioritize a robust, government‑backed digital payment system rather than relying on privately issued stablecoins for mass adoption.